Laying the Groundwork: Why Investing Matters in 2026
For many, the idea of investing can seem daunting, especially if you're just starting out. However, in 2026, building a strong financial foundation that includes investing is more accessible than ever. Personal finance isn't about being inherently skilled with money; it's about cultivating a few consistent habits. These habits include budgeting to understand where your money goes, saving a buffer for unexpected events, managing debt strategically, understanding your credit, and ultimately, allowing your money to grow through investing.
A budget isn't a limitation; it's a strategic roadmap to financial freedom. By dedicating time, particularly at the start of the year, to reassess your spending, prioritize saving, and align your financial decisions with your personal values, you establish a strong trajectory for financial success not just in 2026, but for the years ahead. The key is to begin where you are, with the resources you have, and to build momentum through small, consistent actions rather than attempting dramatic overhauls that often prove unsustainable.
The 50/30/20 Rule: Your Budgeting Blueprint for Investing
One of the most effective and popular budgeting methods for beginners in 2026 is the 50/30/20 rule. This approach is widely favored due to its flexibility and ease of recall. The core principle involves dividing your monthly after-tax income into three distinct categories:
- 50% for Needs: This portion covers essential expenses such as rent or mortgage payments, groceries, utility bills, and minimum debt payments. These are the non-negotiable costs required for daily living.
- 30% for Wants: This category includes discretionary spending like dining out, entertainment, hobbies, and subscriptions. These are expenses that improve your quality of life but are not strictly necessary.
- 20% for Savings and Debt Repayment: This crucial segment is dedicated to building your financial future. It encompasses contributions to your emergency fund, additional debt payments beyond the minimums, and, importantly, your investments.
The 50/30/20 rule simplifies money management, making it easier to allocate funds effectively and ensure that a significant portion of your income is directed towards saving and investing. This method helps you plan where your money goes before it disappears on its own, preventing financial drift and promoting intentional financial growth.
Consistent Saving: The Engine of Your Investment Journey
While many budgeting strategies focus on cutting expenses, the reality is that consistent saving is paramount. According to Debt.com's annual survey, despite a high percentage of Americans claiming to have a budget in 2025, a significant portion still reported living paycheck to paycheck. This highlights that merely having a budget isn't enough; actively adhering to a savings plan is essential.
For beginners in 2026, the goal should be to save and invest at least 20% of your salary each month, as suggested by the 50/30/20 rule. This consistent allocation forms the bedrock of your investment strategy. It's not about making drastic cuts that are hard to maintain, but rather about establishing a steady habit of setting aside money before you have a chance to spend it.
Think of your savings as the fuel for your investment engine. Without consistent contributions, your investments won't have the capital they need to grow. Even small, regular contributions can accumulate significantly over time due to the power of compounding. This emphasizes the importance of starting early and maintaining discipline.
Getting Started with Beginner Investing in 2026
Once you've established a consistent savings habit, the next step is to begin investing. For long-term growth, index funds are widely considered an excellent investment option for beginners. They offer diversification and typically have lower fees compared to actively managed funds, making them a sensible choice for those new to the market.
Here’s a simple breakdown of how to approach beginner investing:
- Automate Your Savings: Set up automatic transfers from your checking account to a dedicated savings or investment account. This ensures that your 20% for savings and investing is allocated before you can spend it.
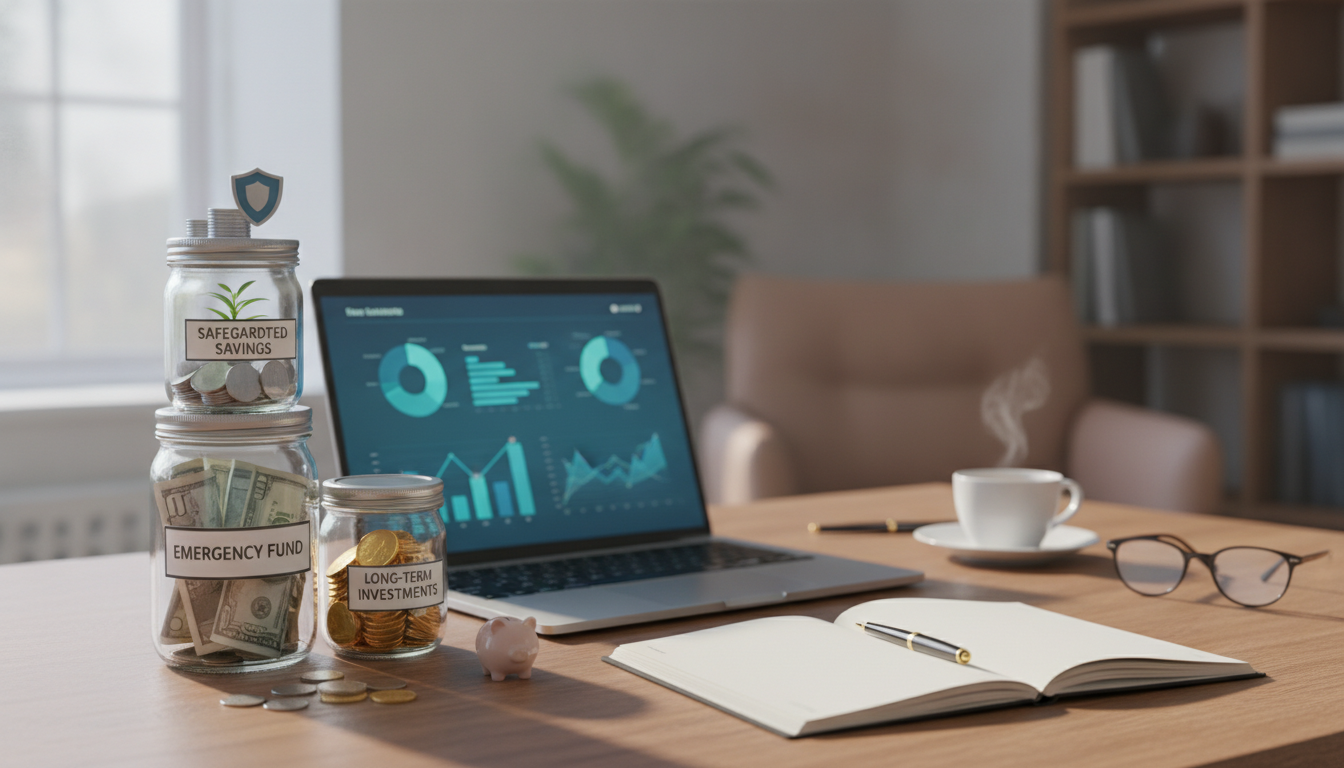
- Build an Emergency Fund: Before significant investing, ensure you have an emergency fund covering 3-6 months of essential living expenses. This provides a financial safety net and prevents you from needing to sell investments prematurely during unexpected events.
- Choose a Brokerage Account: Research and select a reputable brokerage firm that offers low fees and access to index funds or exchange-traded funds (ETFs). Many platforms cater specifically to beginners with user-friendly interfaces.
- Start Small and Be Consistent: You don't need a large sum of money to begin investing. Many platforms allow you to start with small amounts. The key is consistency - regular contributions, even modest ones, are more impactful than sporadic large investments.
- Understand Your Risk Tolerance: While index funds are generally considered lower risk for long-term investors, it's important to understand that all investments carry some level of risk. Educate yourself on the basics of market fluctuations and how they might affect your investments.
Remember, investing is a long-term endeavor. Market values can fluctuate, but over extended periods, well-diversified investments like index funds have historically provided positive returns. The goal is to build wealth steadily over time, not to get rich quickly.
Integrating Investing into Your Financial Values
Aligning your finances with your values is a powerful motivator for consistent financial habits. When you view your budget and investment strategy not as restrictive measures but as tools that enable your long-term goals - whether it’s buying a home, funding education, or securing a comfortable retirement - you’re more likely to stick with them.
In 2026, take the opportunity to reflect on what financial freedom means to you. Is it the ability to pursue a passion, to provide for your family, or to have peace of mind? By connecting your daily financial decisions, including your investment contributions, to these larger aspirations, you transform abstract financial goals into tangible steps towards a desired future.
Building an investment foundation is a journey, not a destination. It requires patience, discipline, and a commitment to continuous learning. By embracing simple, effective strategies like the 50/30/20 rule, prioritizing consistent saving, and making informed investment choices, you can confidently navigate your financial path in 2026 and beyond, setting yourself up for lasting financial stability and growth.